
 edward
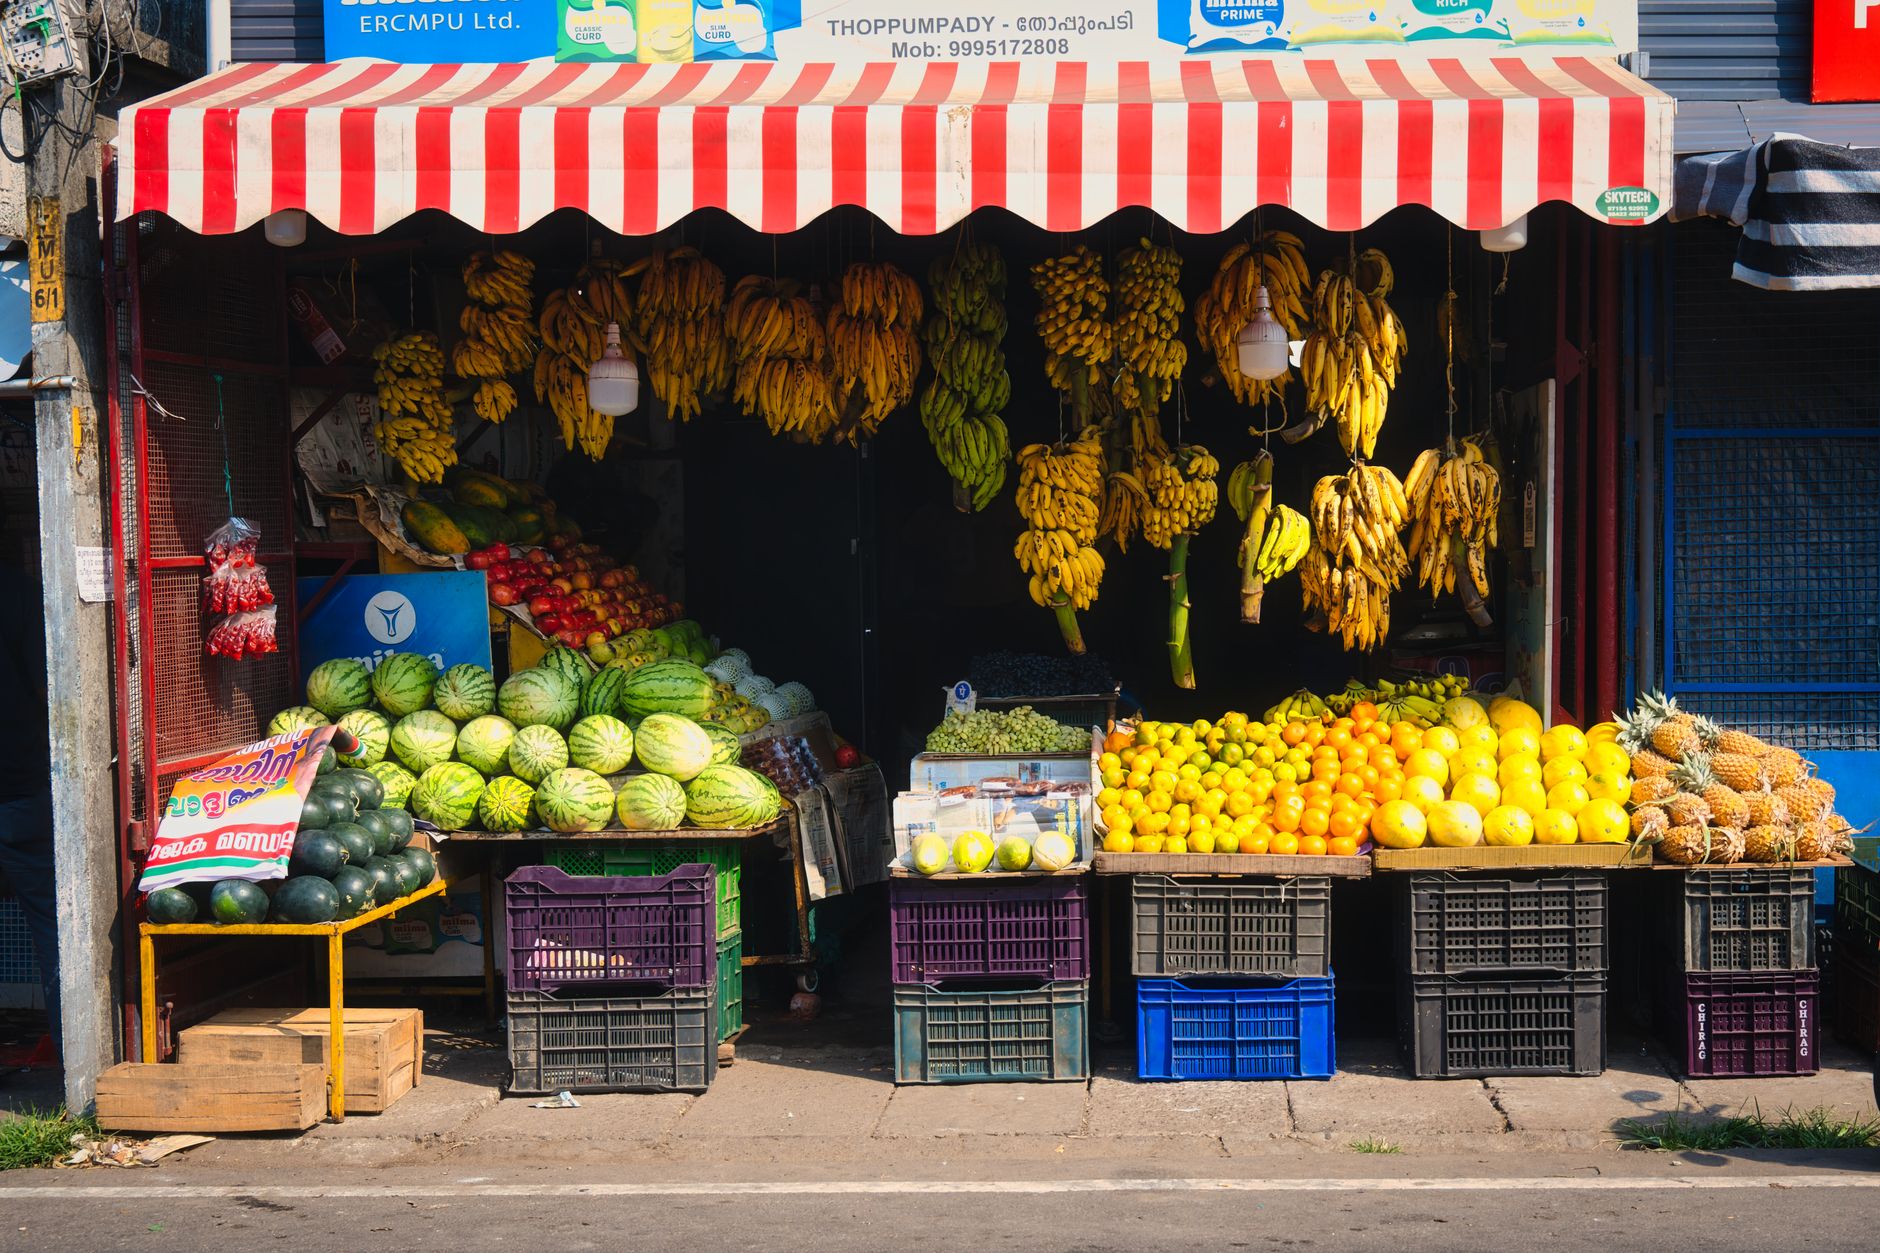
India retail inflation has crossed 6%, prompting speculation about potential RBI actions regarding the repo rate. This situation could significantly affect your monthly EMI payments.
Understanding India’s Retail Inflation
India’s retail inflation has emerged as a pressing concern, particularly as it recently crossed the 6% mark. This surge in inflation is not merely a statistical figure; it directly affects the cost of living for millions of citizens. As prices of essential goods continue to rise, households are feeling the pinch in their monthly budgets.
The Reserve Bank of India (RBI) monitors inflation closely, as it can influence monetary policy decisions, including changes to the repo rate. If the RBI decides to raise the repo rate in response to rising inflation, the implications for borrowers could be significant.
- Increased EMIs: Your equated monthly installments may rise, leading to higher financial burdens.
- Cost of borrowing: Higher rates make loans more expensive, affecting home and vehicle purchases.
- Consumer spending: As households allocate more to essentials, discretionary spending may decline.
Understanding India’s retail inflation is crucial for anticipating these changes and planning accordingly.
What is the Repo Rate?
The repo rate is the rate at which the Reserve Bank of India (RBI) lends money to commercial banks. It plays a crucial role in determining the cost of borrowing for banks, which in turn affects the interest rates offered to consumers. When retail inflation in India rises, as it has recently crossed 6%, the RBI may decide to increase the repo rate to control inflationary pressures.
By raising the repo rate, the RBI aims to make borrowing more expensive, thereby reducing consumer spending and cooling off inflation. This can have a direct impact on your Equated Monthly Installments (EMIs) for loans. Higher repo rates typically lead to increased interest rates on home loans, personal loans, and other forms of credit.
As a result, if you’re currently paying off a loan, you might see your EMIs rise significantly if the RBI implements another rate hike. It’s essential to keep an eye on the repo rate decisions, especially during periods of fluctuating retail inflation, as they can directly impact your financial commitments.
How Inflation Affects EMIs
India’s retail inflation has a direct impact on Equated Monthly Installments (EMIs) for borrowers. When inflation rises, it often leads to an increase in the repo rate set by the Reserve Bank of India (RBI). This, in turn, affects the interest rates on loans, making EMIs more expensive.
As inflation increases, the purchasing power of consumers decreases, leading to higher costs for goods and services. To combat this, the RBI may implement measures to raise interest rates, which can result in:
- Increased EMIs: Higher interest rates translate to a larger portion of monthly payments going towards interest rather than principal.
- Budget Strain: Families may find their budgets strained as more funds are allocated to servicing loans, leaving less for discretionary spending.
- Investment Hesitation: Higher EMIs might deter potential borrowers from taking out new loans, impacting sectors such as real estate and automotive.
Ultimately, the interplay between India’s retail inflation and EMIs can create significant financial challenges for households across the country.
RBI’s Role in Inflation Management
The Reserve Bank of India (RBI) plays a crucial role in managing inflation, particularly in the context of India retail inflation. The central bank’s primary objective is to maintain price stability while ensuring economic growth. To achieve this, the RBI utilizes monetary policy tools, primarily the repo rate, which directly influences lending rates across the economy.
In times of rising inflation, the RBI may decide to increase the repo rate. This action is intended to curb excessive money supply and control inflationary pressures. However, such measures can have a significant impact on borrowers, especially those with floating-rate loans.
When the repo rate increases, banks typically pass on the higher costs to consumers through increased interest rates on loans, including home loans and personal loans. As a result, borrowers may see their Equated Monthly Installments (EMIs) rise, putting additional financial strain on households already grappling with the effects of rising prices.
Monitoring the RBI’s actions is essential for understanding potential changes in India retail inflation and its implications for borrowers.
Potential Outcomes for Borrowers
The recent surge in India retail inflation has sparked concerns among borrowers, particularly in relation to their Equated Monthly Installments (EMIs). As inflation continues to rise, several potential outcomes may emerge for those with loans.
- Increased EMIs: With the Reserve Bank of India (RBI) potentially raising the repo rate to combat inflation, borrowers may face higher EMIs. This adjustment could strain monthly budgets and financial planning.
- Loan Approval Challenges: Stricter lending criteria may be enforced by banks as they navigate the volatile economic landscape, making it harder for new borrowers to secure loans.
- Impact on Consumer Spending: Higher EMIs could lead to reduced disposable income, ultimately affecting consumer spending patterns and overall economic growth.
- Potential for Defaults: Borrowers already struggling with financial commitments may find it increasingly difficult to meet their obligations, raising the risk of defaults.
Understanding these potential outcomes is crucial for borrowers to navigate the challenges posed by India retail inflation effectively.
Tips to Manage Your EMI Payments
As India retail inflation continues to rise, managing your EMI payments becomes increasingly crucial. Here are some tips to help you navigate this challenging financial landscape:
- Review Your Budget: Assess your monthly expenses and identify areas where you can cut back. Prioritize essential spending to ensure you can meet your EMI obligations.
- Consider Loan Restructuring: If you find your EMIs becoming unmanageable, talk to your lender about restructuring your loan. This may involve extending the tenure or lowering the interest rate.
- Increase Your Income: Explore opportunities for additional income, such as freelance work or part-time jobs, to bolster your finances and help cover your EMIs.
- Automate Payments: Set up automatic payments for your EMIs to avoid late fees and ensure you stay on track even during busy times.
- Stay Informed: Keep an eye on the RBI’s policies and how they might impact India retail inflation and your EMIs, allowing you to plan ahead.
By implementing these strategies, you can better manage the pressure of rising costs and maintain your financial stability.
India retail inflation has surged to unprecedented levels, significantly affecting the affordability of everyday goods. As a result, many consumers are finding it increasingly challenging to manage their EMIs amidst rising costs.
Photo by Travel with Lenses on Pexels